Calculate FICA tax and understand 2026 Social Security and Medicare rates, wage limits, paycheck labels and employer matching. This detailed guide explains the numbers, decisions and practical checks involved in FICA tax so that you can move from a headline figure to a more realistic understanding of your money.
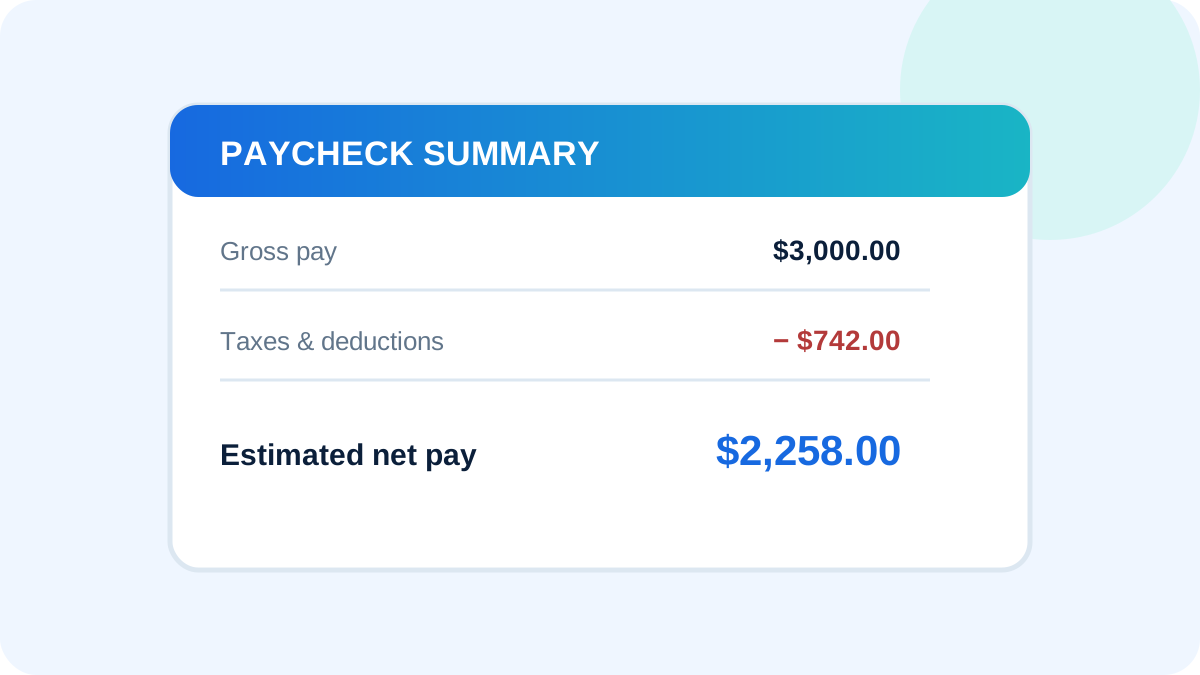
FICA tax is the federal payroll contribution that funds Social Security and Medicare. It is separate from federal income-tax withholding. Most employees see two FICA deductions on each paycheck: Social Security and Medicare.
FICA tax rates for 2026
The regular employee FICA contribution is generally 7.65% of wages covered by both programs: 6.2% for Social Security and 1.45% for Medicare. Employers generally match those regular amounts. For 2026, Social Security tax applies to covered wages up to the $184,500 wage base. Regular Medicare tax has no annual wage ceiling.
How to calculate FICA tax
To estimate FICA taxes on a paycheck, multiply covered Social Security wages by 6.2% and covered Medicare wages by 1.45%, then add the results. For example, if a paycheck has $2,000 subject to both taxes, estimated employee Social Security tax is $124 and Medicare tax is $29, for total regular FICA of $153. Use year-to-date Social Security wages when checking whether the annual wage base has been reached.
Social Security contribution and maximum FICA tax
The 6.2% employee Social Security rate stops applying after covered wages reach the annual wage base. At the 2026 base of $184,500, the maximum employee Social Security tax is $11,439. Medicare does not have the same cap, so there is no single maximum for total FICA tax. Higher earners may also owe Additional Medicare Tax under separate rules.
Does FICA include Social Security and Medicare?
Yes. FICA is the umbrella term for both programs. On a pay stub, Social Security may appear as FICA SS, OASDI or Social Security. Medicare may appear as FICA MED, Medicare, MED or FICA HI. “HI” means Hospital Insurance, the Medicare portion of the payroll tax.
Why is FICA tax so high on my paycheck?
FICA may feel high because the regular employee contribution can total 7.65% before federal, state or local income-tax withholding is considered. A bonus or larger paycheck can also create a larger dollar deduction even when the regular rate is unchanged. Compare the FICA amount with the Social Security and Medicare taxable-wage lines, not only gross pay.
Where is FICA on a paycheck?
Look in the taxes or employee deductions section for two lines: one for Social Security and one for Medicare. Divide each current deduction by its corresponding current taxable wage to check the approximate rate. Then review year-to-date wages and taxes. Ask payroll about any unexplained difference, especially after changing benefits or working for multiple employers.
Why deductions do not always reduce FICA wages
A contribution that reduces federal taxable income does not necessarily reduce Social Security or Medicare wages. Traditional 401(k) salary deferrals are a common example. Qualified health benefits may receive different treatment. This is why gross pay, federal taxable wages, Social Security wages and Medicare wages can show different amounts.
FICA tax for self-employed workers
Independent workers generally pay Social Security and Medicare through self-employment tax and account for both the employee-like and employer-like portions, subject to the applicable calculation. Estimated tax payments may also be needed because a client does not routinely withhold payroll tax.
Why FICA tax matters for real-world planning
Payroll information is easy to underestimate because an annual salary or hourly rate is usually the most visible number. Daily financial decisions, however, are funded by the amount deposited after withholding and deductions. A useful analysis connects the annual number to each pay period, identifies mandatory taxes, separates voluntary benefits and accounts for the state and locality in which the work is performed.
Consider a worker separating Social Security and Medicare from federal income-tax withholding. The correct answer is rarely found by applying one flat percentage. Filing information, pay frequency, taxable benefits, retirement contributions and state rules can all change the result. The goal is not to predict a paycheck to the cent without payroll records. The goal is to build a transparent estimate, understand the assumptions and know what to verify when the actual statement arrives.
Use the Selvox US Paycheck Calculator to test a salary or hourly figure. Change one input at a time and record the difference. This makes the calculator a comparison tool rather than a black box and helps explain which choices have the greatest effect on estimated take-home pay.
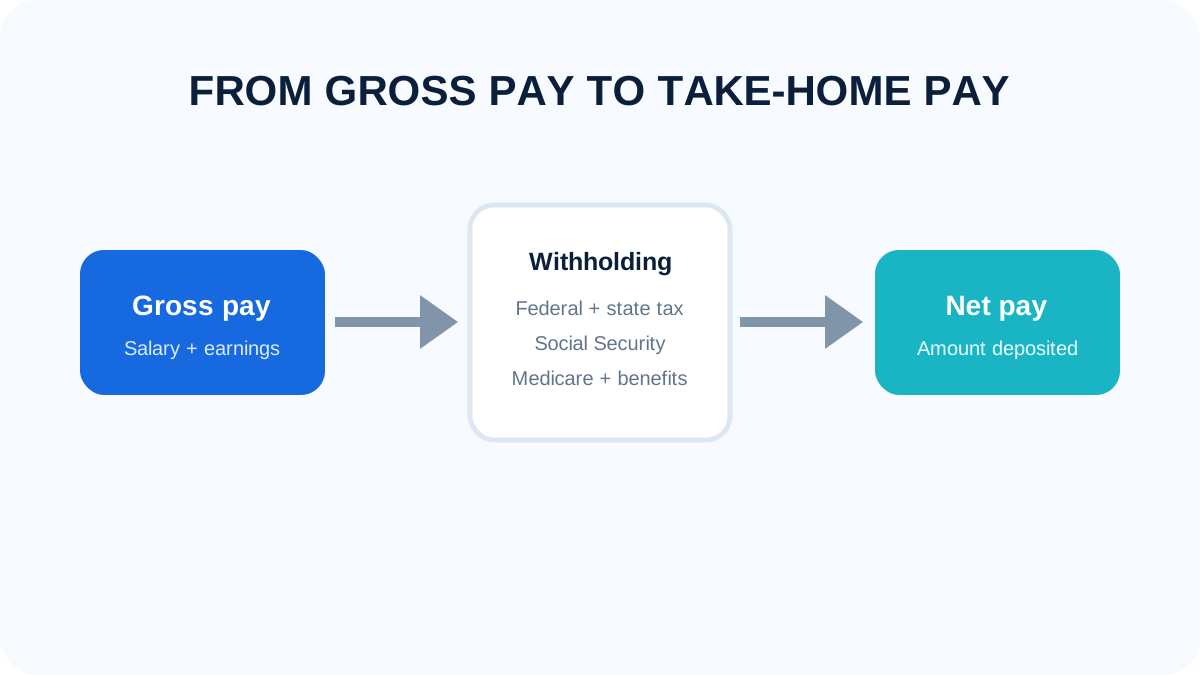
A step-by-step method you can reuse
- Confirm the gross annual salary or hourly rate and identify any expected overtime, bonuses, commissions or unpaid periods.
- Identify the pay schedule. Weekly, biweekly, semimonthly and monthly payrolls divide annual compensation differently.
- List deductions that may reduce taxable wages, but check which taxes each deduction actually affects.
- Estimate federal income-tax withholding using the correct filing status and current information rather than a remembered flat percentage.
- Calculate the employee portions of Social Security and Medicare separately from federal income tax.
- Include state withholding and investigate city, county or school-district payroll taxes where they may apply.
- Subtract post-tax deductions and compare the result with both annual and per-pay-period expectations.
- Review the first complete pay stub and update the estimate when real payroll data differs from an assumption.
How to compare two compensation scenarios
When comparing jobs, schedules or benefit elections, keep the assumptions consistent. Use the same filing status and household information, then change only the salary, state, pay frequency or benefit in question. Record gross pay, estimated taxes, employee benefit costs and net pay for each version. A side-by-side table prevents a larger check from hiding weaker health coverage, a longer commute or a smaller employer retirement contribution.
Annualize every recurring amount. A difference of $35 per biweekly check becomes $910 across 26 checks. A $150 monthly premium becomes $1,800 per year. Small payroll entries can therefore matter more than they appear to on a single statement. Also separate cash compensation from employer-paid value, because an employer contribution may improve total compensation without increasing the bank deposit.
Common mistakes to avoid
Combining FICA with income tax
This mistake can distort an estimate and lead to an unrealistic budget. Replace the assumption with a documented number from an offer letter, benefit guide, official tax source or pay stub. If the exact value is unavailable, label the estimate clearly and test a reasonable range rather than presenting one uncertain figure as guaranteed.
Forgetting the Social Security wage base
This mistake can distort an estimate and lead to an unrealistic budget. Replace the assumption with a documented number from an offer letter, benefit guide, official tax source or pay stub. If the exact value is unavailable, label the estimate clearly and test a reasonable range rather than presenting one uncertain figure as guaranteed.
Assuming all deductions reduce FICA wages
This mistake can distort an estimate and lead to an unrealistic budget. Replace the assumption with a documented number from an offer letter, benefit guide, official tax source or pay stub. If the exact value is unavailable, label the estimate clearly and test a reasonable range rather than presenting one uncertain figure as guaranteed.
Confusing employee and employer portions
This mistake can distort an estimate and lead to an unrealistic budget. Replace the assumption with a documented number from an offer letter, benefit guide, official tax source or pay stub. If the exact value is unavailable, label the estimate clearly and test a reasonable range rather than presenting one uncertain figure as guaranteed.
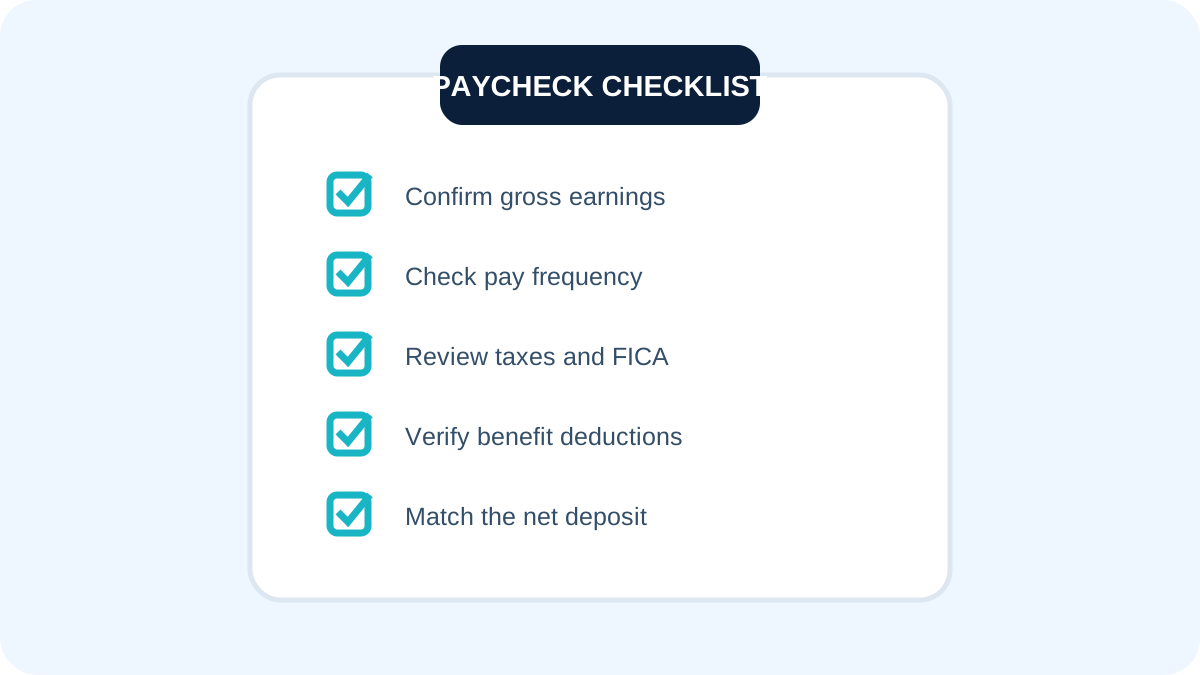
A practical paycheck review checklist
- Confirm the employee name, employer and pay-period dates.
- Check salary, regular hours, overtime hours and additional earnings.
- Compare gross pay with federal, Social Security, Medicare and state taxable wages.
- Review every tax line and compare current amounts with year-to-date totals.
- Confirm health, retirement and other benefit elections.
- Distinguish employee deductions from employer-paid contributions.
- Match net pay with all direct-deposit allocations.
- Ask payroll promptly about an unfamiliar or unexpected entry.
Using estimates responsibly
A calculator is most useful for planning and comparison. It cannot automatically know every detail on a Form W-4, every state allowance, local tax, bonus method, credit or employer benefit rule. Treat the output as a well-organized estimate and use actual payroll documentation for reconciliation. For tax filing, complex multi-state work or a major financial decision, consult official guidance or a qualified professional.
Revisit the calculation after a raise, job change, move, marriage, divorce, new dependent, benefit enrollment or change in outside income. A model that was reasonable at the beginning of the year can become outdated when household or employment facts change.
Frequently asked questions
Can an online calculator match my paycheck exactly?
Usually not to the cent. Payroll systems use detailed federal, state, local and benefit information. A calculator is a planning estimate that becomes more useful when its assumptions match your actual forms and deductions.
Should I use gross or net income for a budget?
Use reliable net deposits for recurring spending. Gross income remains useful for comparing compensation and calculating savings rates, but it is not the amount available to pay bills.
Why did my withholding change when salary did not?
A new tax year, benefit election, bonus, payroll correction, updated form or reaching an annual wage threshold can change withholding even when base salary is unchanged.
Do pre-tax deductions reduce every tax?
No. The tax treatment depends on the deduction. Some amounts reduce federal taxable income but remain subject to Social Security or Medicare, while other qualified benefits receive different treatment.
How often should I review payroll information?
Review every statement briefly and perform a deeper check after major changes. Catching an incorrect rate, missing hours or wrong benefit election early makes correction easier.
Where should I continue reading?
Explore the Selvox blog and related payroll guides, then use the calculator to test the examples with your own figures.
Related Selvox resources
Federal Income Tax Withholding · How To Read A Pay Stub · Pre Tax Vs Post Tax Deductions · Browse all paycheck and tax guides.
Final takeaway
FICA Tax 2026: Rates, Calculation, Social Security and Medicare becomes easier to understand when each number has a clear source. Begin with gross earnings, work through taxes and deductions in the correct order, compare annual and per-check totals, and verify the estimate against payroll documents. That process produces a more dependable plan than relying on a single percentage or generic rule of thumb.
Estimate your take-home pay
Use salary, state and filing status to see a quick breakdown.